Blue Origin’s reported $10 billion financing offers exposure to strategic space infrastructure, but valuation, execution, governance, and liquidity require close scrutiny.
Reported outside financing would validate Blue Origin’s industrial scale, but allocators must weigh government demand and strategic infrastructure against execution and liquidity risk.
Blue Origin’s reported first external financing would transform the company from a founder funded aerospace project into an institutionally priced private market asset. At a reported $130 billion valuation before new capital, the investment case depends on converting industrial capability into repeatable revenue.
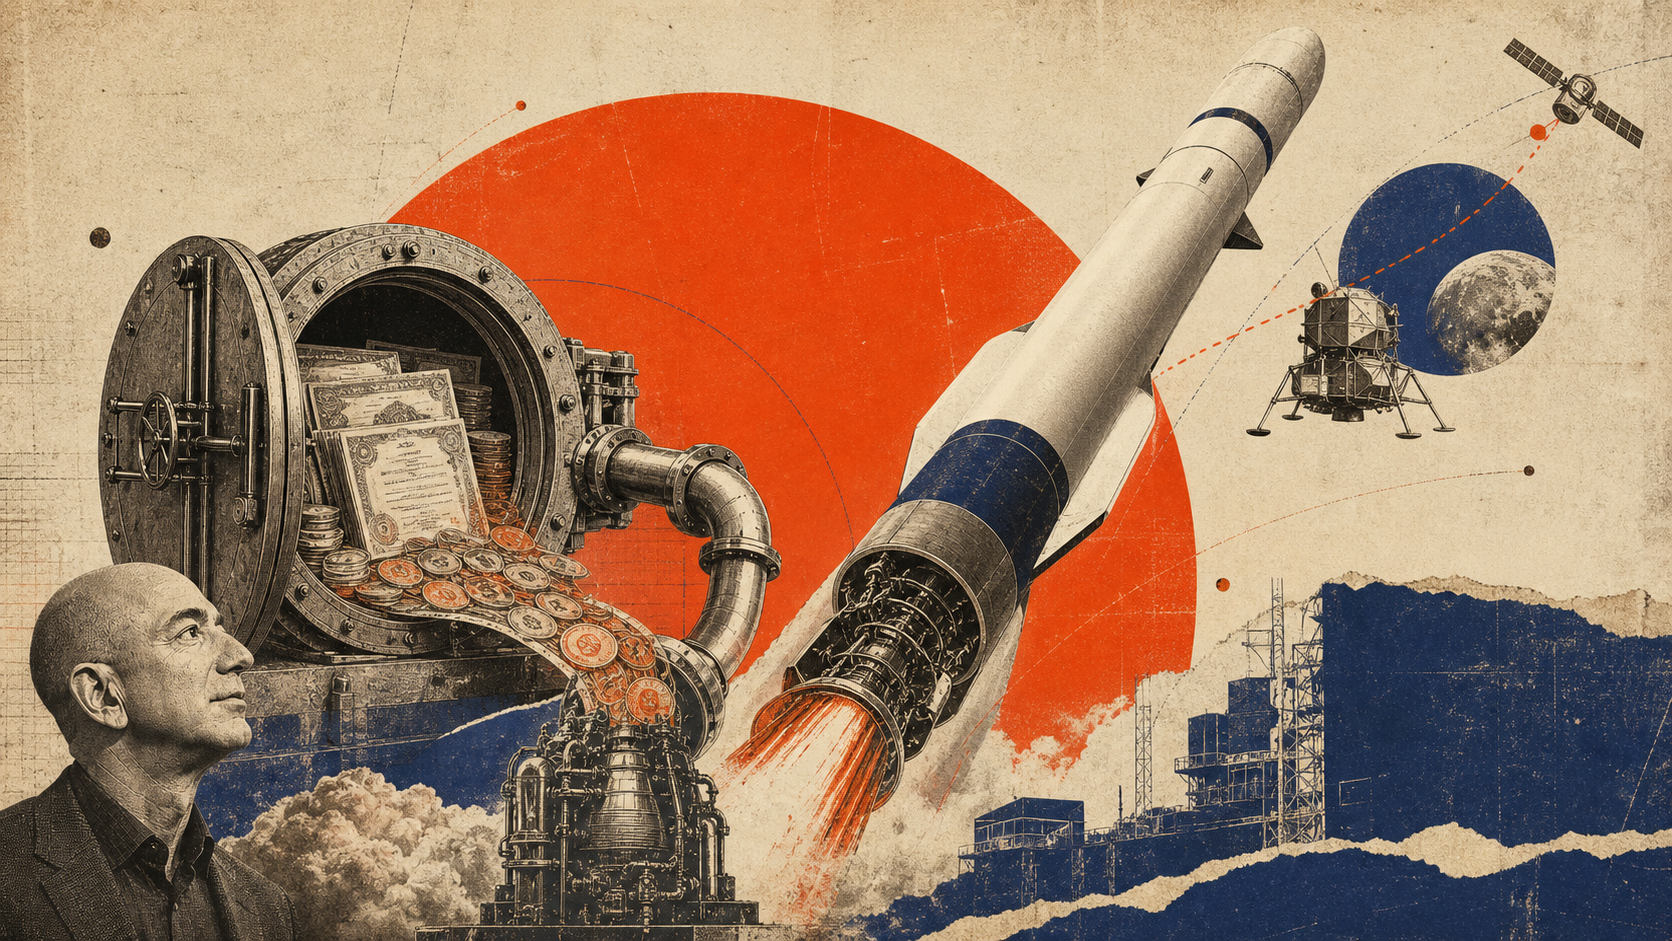
Reports indicate that Blue Origin is seeking approximately $10 billion, with Coatue expected to contribute $4 billion and Jeff Bezos another $2 billion. The financing has been described as the company’s first outside capital round, although Blue Origin has not publicly confirmed its completion or disclosed the proposed security terms. Estimates that Bezos has invested about $28 billion since the company’s formation are also based on external analysis rather than audited company reporting. Allocators therefore need visibility into valuation mechanics, liquidation preferences, governance rights, dilution protection, and the intended use of proceeds before treating the reported price as established market value.
The revenue opportunity is supported by credible institutional customers. NASA awarded Blue Origin a $3.4 billion firm fixed price contract to develop a crewed lunar landing system for Artemis V. Space Systems Command separately assigned an anticipated value of about $2.39 billion to Blue Origin under the National Security Space Launch program, with seven missions projected to begin receiving assignments after the initial order year. That confirmed figure is materially below the $8 billion sometimes associated with the broader opportunity. Government contracts can provide durable demand, but payments remain dependent on milestones, certification, procurement schedules, and technical delivery.
Commercial demand extends beyond government programs. Amazon selected New Glenn for 12 Project Kuiper launches and retained options for 15 more. The arrangement provides a potentially significant launch manifest, although the economic value will depend on launch cadence, reliability, pricing, and the exercise of optional missions. For allocators, contracted volume is not equivalent to recognized revenue. Backlog quality must be assessed alongside cancellation rights, milestone structure, customer concentration, and the capital required to deliver each mission.
Blue Origin’s strongest strategic asset may be its integrated industrial footprint. The company combines rocket development in Washington, engine production in Alabama, testing in Texas, and launch manufacturing and operations in Florida. Its BE 4 methane engine powers both New Glenn and United Launch Alliance’s Vulcan rocket, creating exposure beyond Blue Origin’s own launch schedule. United Launch Alliance states that each Vulcan booster uses two BE 4 engines, giving Blue Origin a position inside a national security launch system operated by another provider. This integration may support operating leverage, but it also concentrates technical and manufacturing risk across several programs.
Execution remains the central underwriting variable. New Glenn reached orbit on its first flight, establishing an important technical milestone, but orbital access alone does not prove repeatable launch economics or booster reuse. NASA’s inspector general has also identified design and schedule challenges affecting the lunar lander program. A platform spanning engines, launch vehicles, lunar systems, and satellites increases the available revenue pool, yet each additional program competes for engineering capacity and capital. Integration can create strategic value. It can also magnify delays.
The reported valuation places substantial weight on future scale. Private space benefits from rising defense expenditure, geopolitical competition, satellite demand, and government interest in launch resilience. These secular drivers can support long duration capital deployment, but the company remains exposed to technical failure, procurement delays, customer concentration, further financing requirements, and a limited secondary market. Scarcity of access should not be confused with valuation support. An exclusive allocation can still deliver weak returns if entry pricing absorbs most of the future value creation.
Institutional investors should monitor whether the round closes on the reported terms, how much capital is primary, what investor protections accompany the financing, and whether the proceeds accelerate commercial delivery. New Glenn launch cadence, booster recovery, BE 4 production, Kuiper deployment, Artemis milestones, national security certification, cash consumption, and the path to liquidity will determine whether Blue Origin becomes a durable private space platform or an exceptionally capital intensive industrial venture.