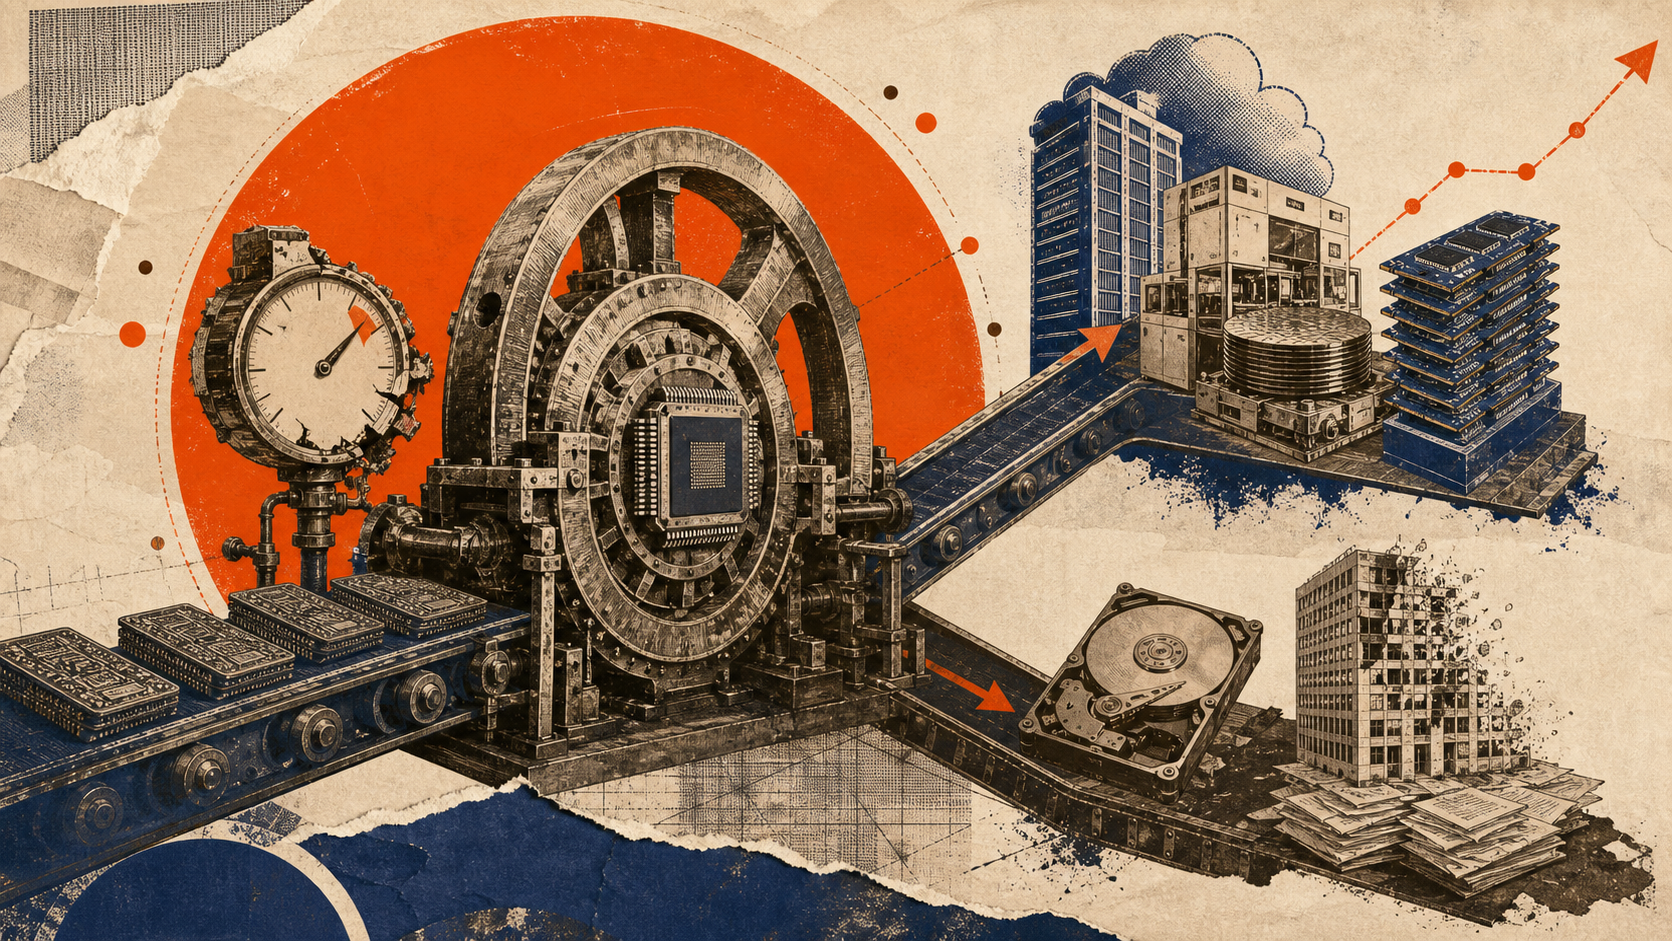
Analyst revisions across Microsoft, Applied Materials, Micron, Western Digital, and HubSpot reveal a more selective AI market focused on earnings durability.
Analyst revisions across cloud, chips, memory, storage, and software show that AI exposure is fragmenting as investors demand clearer evidence of durable returns.
The artificial intelligence trade is becoming an earnings test. Capital is rotating toward companies that can demonstrate enterprise adoption, pricing power, supply discipline, or strategically valuable infrastructure, while businesses with uncertain monetization face a higher cost of investor patience.
Goldman Sachs added Microsoft and Applied Materials to its United States Conviction List as two expressions of the next investment phase. Microsoft offers exposure to enterprise adoption through Azure, improving AI unit economics, and Copilot monetization, with Goldman expecting earnings growth to accelerate from 12% in fiscal 2027 to more than 20% by fiscal 2029. Applied Materials represents the physical layer, where demand for advanced deposition and etching tools could support market share gains at memory manufacturers and leading foundries. For allocators, the pairing suggests that value may migrate toward both enterprise distribution and the equipment required to sustain compute intensity.
The broader risk is increasingly concentrated in earnings assumptions rather than valuation multiples. Goldman Sachs Research has noted that the valuation premium of the five largest United States technology companies has almost disappeared, while the global software premium has declined to roughly 20% from almost 200% around the peak of the dot com cycle. Yet implied long term earnings growth has continued rising. Capital expenditure by cloud and computing companies has also accelerated, placing greater pressure on free cash flow and increasing reliance on debt and equity financing. Prices need not look historically extreme for returns to disappoint if projected earnings prove temporary. Goldman Sachs Research
Micron illustrates the constructive side of that argument. Bank of America retained its Buy rating and $1,550 target after the recent share price decline, describing the pullback as an improved entry opportunity. The bank estimates fiscal 2028 earnings near $150 per share and argues that earnings could remain around $100 even if memory pricing follows a historical downturn. Long term agreements covering an expected 50% to 70% of capacity could reduce revenue volatility, while demand for high bandwidth memory provides exposure to AI systems that commodity memory competitors cannot easily serve. The allocator question is whether those structural improvements are sufficient to reduce the cyclicality historically embedded in memory valuations.
Western Digital presents the opposite challenge. Summit Insights downgraded the company as its transition to heat assisted magnetic recording introduces execution costs and potential gross margin pressure during 2027. Long term supply agreements may protect demand visibility but could limit pricing upside, while weakness in personal computer and consumer storage markets can offset data center momentum. The shares declined 13% after results, despite guidance exceeding analyst expectations, because a strong recent performance had already discounted continued operational outperformance. AI infrastructure demand remains supportive, but technology transitions can still destroy value within an expanding market.
Software is facing a different form of scrutiny. HubSpot received three downgrades after reporting slower customer growth, cautious guidance, and limited visibility into an AI driven reacceleration. Net customer additions of approximately 7,000 fell below expectations of 9,000 to 10,000, while the company projected third quarter revenue growth of 15% and reduced its full year outlook. The underlying business may remain viable, but enterprise budget sensitivity, longer sales cycles, and uncertain AI adoption timing reduce the probability of an immediate earnings inflection. Software exposure cannot be treated as an automatic beneficiary of AI deployment.
The macro regime increases the importance of this differentiation. Higher capital requirements and elevated interest rates raise the hurdle for every dollar invested in compute, memory, storage, and software development. At the same time, the AI capital expenditure cycle is supporting industrial demand and shifting market leadership beyond traditional technology. Lower stock correlations and greater earnings dispersion can improve the opportunity set for active managers, but they also weaken the protection offered by broad thematic baskets.
Investment committees should monitor enterprise AI revenue, cloud unit economics, semiconductor equipment orders, memory contract coverage, storage transition costs, software retention, and the financing burden created by the capital expenditure cycle. The next stage of AI investing will not be determined by whether the technology expands. It will be determined by which companies convert that expansion into persistent free cash flow.